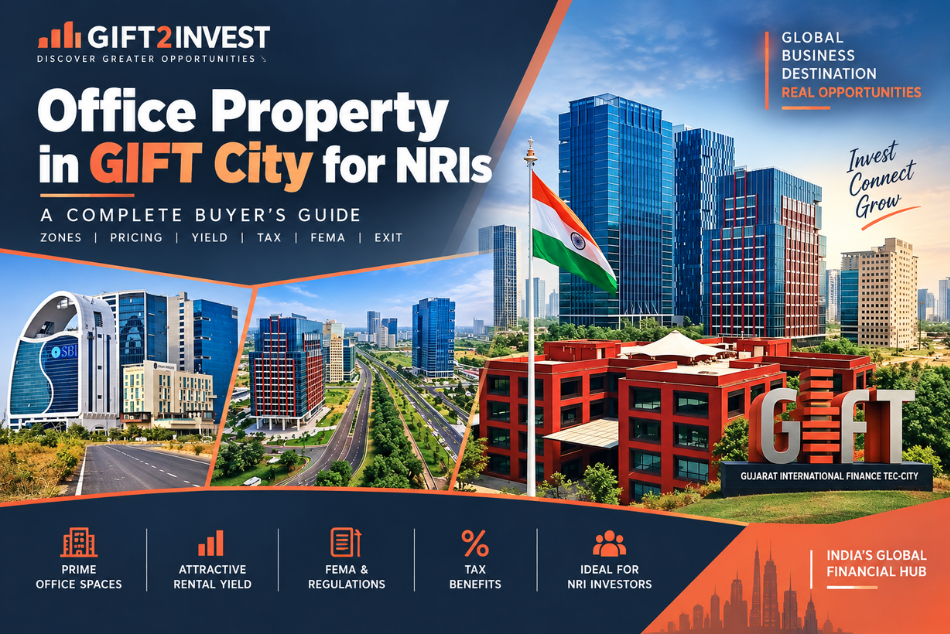
Office Property in GIFT City for NRIs: Where to Start
Buying office property in GIFT City for NRIs is not the same process as buying a flat back home in Ahmedabad or Vadodara. The zone matters. The currency matters. The regulator matters. And the tenant you can legally lease to depends entirely on which part of the city your unit sits in. This guide walks through the full picture — eligibility, zones, pricing, yield, tax, FEMA, financing, and exit — so an NRI evaluating a commercial purchase here knows exactly what they are buying before they sign anything.
GIFT City has crossed 1,147 IFSCA registrations and authorisations, with banking assets in the ecosystem past USD 111 billion as of March 2026. That scale is real, not projected. But scale alone does not tell an NRI buyer whether a specific office unit will lease easily, whether the tax treatment matches what a brochure implied, or whether the exit route works the way it should. Those are the questions this article actually answers.
Can an NRI Actually Buy Office Property in GIFT City?
Yes. NRIs and OCIs can purchase commercial and residential property in GIFT City under the Reserve Bank of India’s general permission route for immovable property in India. There is no separate GIFT City-specific eligibility test layered on top of this — the same FEMA framework that governs an NRI buying an office in Pune or Gurugram applies here.
A few restrictions carry over from the standard national rules, and they apply in GIFT City exactly as they do everywhere else. Citizens of Pakistan, Bangladesh, Sri Lanka, Afghanistan, China, Iran, Nepal, Bhutan, Hong Kong, and Macau need specific prior RBI approval before acquiring property in India, regardless of OCI or PIO status. Agricultural land, plantation property, and farmhouses remain off-limits to NRIs and OCIs everywhere in India, GIFT City’s surrounding zones included — though this has no bearing on office purchases inside the city’s commercial towers.
Payment has to move through banking channels using permissible NRE, NRO, or FCNR routes. There is no cap on how many commercial units an NRI can own, and no minimum residency requirement to qualify. For most NRIs and OCIs reading this, the eligibility question resolves quickly — the harder decisions come after.
IFSC vs DTA: The First Decision an NRI Buyer Has to Make
GIFT City has two commercial zones, and this is the single most consequential distinction for anyone buying office property in GIFT City for NRIs seeking rental income specifically.
The SEZ, home to the International Financial Services Centre, is built for entities that hold IFSCA registration — banks, fund managers, insurance firms, aircraft leasing SPVs. Space inside the SEZ boundary is meant for occupation by SEZ-registered businesses. An NRI buying purely as a passive investor, with no IFSC-registered business of their own and no structured leasing arrangement in place, does not get a straightforward, open-market rental asset by buying here. The tenant pool is restricted by regulation, not by market forces.
The Domestic Tariff Area works differently. Businesses here operate under standard Indian rules, in rupees, without needing IFSCA registration to occupy space. DTA office units can be leased to any domestic company — Global Capability Centre support functions, professional services firms, IT and fintech companies that have not gone through IFSCA registration. For an NRI who wants a conventional landlord model — buy, lease, collect rent, renew — the DTA is where that model is actually available.
| Factor | SEZ/IFSC | DTA |
|---|---|---|
| Who can occupy | SEZ-registered entities only | Any domestic company |
| Open-market leasing for NRI landlord | Not straightforward | Standard landlord model |
| Currency of operation | Foreign currency | Indian rupees |
| Typical gross yield | 6% – 10% | 5% – 7% |
| Best suited to | Own IFSC entity, or a structured lease arrangement | Passive rental income buyer |
Neither zone is objectively better. They answer different questions. An NRI planning to eventually set up their own IFSC-registered fund, advisory, or family office structure has a real reason to consider SEZ space. An NRI purely looking for rental income from an office asset is, in almost every case, better served starting the search in the DTA.
What Kinds of Office Property Are Actually Available
Within both zones, GIFT City’s commercial stock breaks into a few recognisable formats, and each suits a different NRI investor profile.
Grade-A Institutional Floor Plates
Full or multi-floor tenancies aimed at large financial entities — international banks, fund managers, insurance operations. Long leases, typically five to ten years, with institutional fit-out requirements: raised flooring, power redundancy, financial-grade broadband. Entry price is the highest of the three formats, and vacancy risk is generally the lowest.
Co-working and Managed Office Space
Smaller footprints serving compliance offices, representative presences, and small fund teams. Per-square-foot yield runs higher because the operator captures a premium for flexibility, but occupancy is more variable than a long-leased Grade-A floor.
Boutique Private Offices
Formats of roughly 2,000 to 6,000 square feet, aimed at family offices, aircraft leasing SPVs, and advisory firms that want dedicated, private space without a full floor. This segment is currently undersupplied relative to demand from wealth management and aviation finance entities — a detail worth knowing for an NRI comparing several shortlisted units.
DTA Business-Park Style Offices
Standard commercial units for GCC support functions, professional services firms, and domestic IT or fintech tenants. This is the format most directly comparable to a conventional office purchase anywhere else in India, and the one most straightforward for a first-time NRI commercial buyer.
Pricing: What an NRI Should Actually Budget for
Current listings across GIFT City put commercial office rates broadly in the Rs. 6,000 to Rs. 14,000 per square foot range. Premium, plug-and-play units with institutional-grade specifications sit at the upper end. Larger bare-shell floor plates in mid-tier buildings run closer to the lower end.
For a commercial purchase where SEZ-registered tenancy matters — banks, aircraft leasing SPVs — pricing tends to track toward the upper part of that band, reflecting the tenant covenant quality the zone can offer. DTA pricing for a comparable specification typically comes in a notch lower, since the tenant pool is broader but not policy-anchored the same way.
For an NRI comparing GIFT City against a familiar home-country reference point, this is a fraction of what comparable financial-district commercial space costs in Mumbai’s BKC, and broadly in line with or below Bengaluru’s central business district — while carrying a materially different tenant demand structure underneath it.
Rental Yield: What GIFT City Office Property Actually Delivers
Gross rental yields on leased, quality office space in GIFT City currently run 6% to 10%, depending on zone, building specification, and tenant profile. Some managed and co-working formats advertise figures around 11%, though that number often reflects operator-level economics rather than what a passive landlord actually takes home.
Net yield — after maintenance, property management, and a realistic vacancy allowance — typically lands two to three percentage points below the gross figure. A well-leased IFSC unit quoted at 8% gross is often closer to a 5.5% to 6% net proposition once those costs are factored in honestly.
For context, a bank fixed deposit currently pays 6.5% to 7.5% pre-tax with full liquidity and zero effort. On net yield alone, GIFT City office property has to work to justify its illiquidity. It generally does, once capital appreciation is added to the return stack — which is exactly what a five-to-seven-year hold in this market is built to capture.
Taxation for an NRI Owning Office Property in GIFT City
This is the point most sales conversations blur, and it deserves a direct answer. The IFSC’s well-publicised tax holidays — the profit exemptions, GST relief, exemptions on STT and CTT — apply to businesses registered and operating inside the SEZ. They do not extend to the property owner as a passive investor, NRI or otherwise.
Rental income earned by an NRI from GIFT City commercial property is taxed under standard Indian income tax rules, at the applicable NRI rate, with TDS obligations falling on the tenant or the managing agent. Capital gains on eventual sale follow the same standard framework applied to any Indian property. No part of the IFSC’s corporate tax architecture carries over to a residential or commercial property owner who is simply renting the space out.
This does not weaken the case for office property in GIFT City for NRIs. It simply means the decision should rest on yield, appreciation, and tenant quality — not on an assumed personal tax advantage that was never designed for a passive property owner in the first place. A chartered accountant familiar with both real estate taxation and IFSC regulations should confirm the specific position before any purchase agreement is signed.
FEMA and Repatriation, in Practical Terms
Property acquisition follows FEMA and RBI’s general permission route, with payment routed through NRE, NRO, or FCNR channels depending on funding source. Repatriation of sale proceeds is permitted, subject to the applicable conditions. For residential property, the simplified route is capped at two properties in a lifetime for NRE or FCNR-funded purchases; commercial property repatriation follows the standard remittance framework, and NRO-funded proceeds are subject to the usual annual remittance cap.
For outward remittances made on or after 1 April 2026, the reporting and CA-certification requirements should be checked against Forms 145 and 146 under the current Income Tax Rules. Getting a CA relationship in place before a sale — not after — avoids a documentation scramble at the exact moment an NRI is trying to move capital out.
Financing an Office Purchase From Abroad
Standard Indian banks extend commercial property loans to NRIs, typically at a lower loan-to-value ratio than what a resident Indian buyer would get — commercial purchases generally see 60% to 70% financing against a higher equity contribution. Some lenders have materially more experience with GIFT City transactions than others, and that experience shows up in how smoothly the documentation and disbursement process runs.
A higher equity contribution reduces carry cost meaningfully. On a leased unit yielding 6% gross, borrowing at a market commercial rate can leave a comfortable margin once maintenance and vacancy allowance are subtracted. On a vacant unit with no tenant in place, that margin disappears fast, and an NRI managing the loan from abroad should model the vacant-unit scenario honestly before committing to a high loan-to-value structure.
A registered Power of Attorney is the standard mechanism for an NRI who cannot be physically present for every registration and possession formality. Legal counsel in Gujarat with SEZ and RERA experience should draft this specifically for a GIFT City transaction — a generic POA template drafted for a residential purchase elsewhere in India often misses SEZ-specific clauses.
Due Diligence Before Signing
- Confirm zone classification — IFSC or DTA — from the GIFT City Development Corporation’s allotment document, not the developer’s brochure.
- For SEZ purchases, confirm your route to a qualifying tenant before assuming rental income. This is the single most common reason a retail NRI buyer ends up with a unit that does not perform as expected.
- Check the floor specification sheet — power redundancy, raised flooring, financial-grade connectivity — against what institutional tenants actually require.
- Ask for the developer’s GIFT City-specific delivery history, not their broader Gujarat or pan-India track record. Delivering inside a Special Investment Region involves approvals a standard project never encounters.
- Verify RERA registration and cross-check the stated possession date against the developer’s actual history of hitting or missing prior deadlines.
- Confirm whether an existing tenant or a signed letter of intent is already in place. A leased unit and a vacant one are different risk categories, not different flavours of the same investment.
- Get the maintenance charge per square foot in writing, and run your net yield number against that figure rather than the gross number in the listing.
Exit Considerations for an NRI Investor
GIFT City’s secondary commercial market is improving but still thinner than an established address like Mumbai’s BKC or Bengaluru’s CBD. A well-leased IFSC unit with an institutional tenant on a long lease has a realistic institutional buyer universe — REITs, PE funds, and family offices are all active in quality GIFT City commercial stock above a certain scale.
For a smaller individual unit, the buyer pool is narrower and more dependent on the retail secondary market forming around it. An NRI planning a shorter holding period — under five years — should weight this liquidity constraint heavily before committing, since a forced exit on a tight timeline in GIFT City may take longer to close than the equivalent exit in a mature market back home.
A leased unit at the point of sale is meaningfully easier to exit than a vacant one, for the same reason it is easier to lease in the first place — income visibility reduces buyer hesitation. Holding through to a point where the lease term overlaps with your intended exit window is a simple but underused strategy among NRI sellers here.
Office Property in GIFT City for NRIs Across Different Budgets
Not every NRI evaluating GIFT City commercial property is working with the same capital block, and the right entry point differs meaningfully by scale.
Smaller Ticket Buyers
A single DTA office unit — a few hundred to a couple of thousand square feet — is the accessible entry point for most first-time NRI commercial buyers. The conventional landlord model works cleanly here, and the due-diligence burden is lower than an SEZ purchase.
Mid-Scale Investors
NRIs deploying a larger single block, or looking specifically at boutique SEZ-adjacent formats for a family investment structure they plan to operate themselves, sit in this tier. The zone decision becomes more consequential here, since an operational IFSC presence changes what SEZ space can deliver beyond passive yield.
HNI and Family-Office Scale
Above roughly Rs. 25 to 30 crore, the conversation shifts from buying a unit to structuring a position — whole floors, forward-purchase agreements with developers, or a corporate holding entity built for depreciation advantages and a cleaner institutional exit. Family offices at this scale increasingly pair an SEZ anchor asset with a broader DTA holding, diversifying tenant exposure while keeping a policy-backed core. This is also where the Foreign Family Investment Fund framework, approved by IFSCA in April 2026, becomes genuinely relevant — it gives large foreign family capital a structure that can consolidate financial activity and real estate exposure under one regulatory roof, though it is not a property-holding vehicle in itself and works alongside, not instead of, the real estate decision.
Across every budget tier, the underlying principle for office property in GIFT City for NRIs stays the same: match the zone and format to the actual objective — income, operational base, or long-horizon appreciation — before comparing listings on price alone.
Wrapping Up
Office property in GIFT City for NRIs is a genuinely available, well-regulated opportunity — but it rewards buyers who treat the zone decision, the tax picture, and the financing structure as separate, specific questions rather than assuming a single generic property checklist covers all of it. Confirm eligibility, pick the zone that matches your actual goal, price your maintenance and vacancy realistically, and get FEMA and repatriation mapped out before, not after, capital moves. GIFT2Invest.com carries current GIFT City commercial listings with zone classification and developer details specified upfront — a practical starting point for turning this guide into an actual shortlist.
FAQs: Office Property in GIFT City for NRIs
Q1) Do I Need a PAN Card to Buy Office Property in GIFT City as an NRI?
A PAN card is typically required for property registration and for tax compliance on rental income. Confirm the exact documentation requirements with a qualified legal advisor, since the structure varies depending on whether you buy as an individual or through an entity.
Q2) Can I Buy SEZ Office Space Purely as a Rental Investment?
Not in the straightforward, open-market sense. SEZ space is meant for occupation by SEZ-registered entities. As a passive NRI investor with no IFSC-registered business and no structured leasing arrangement, the DTA is the more reliable route to conventional rental income.
Q3) What Loan-to-Value Can an NRI Expect on a GIFT City Commercial Purchase?
Commercial financing for NRIs generally runs at a lower loan-to-value than residential — commonly 60% to 70% — with the balance funded through equity. Some Indian lenders have more GIFT City-specific experience than others, which is worth asking about directly before choosing a bank.
Q4) Are IFSC Tax Benefits Available to Me as a Property Owner?
No. The IFSC’s profit exemptions and transaction tax holidays apply to the businesses operating inside the zone, not to the property owner. Rental income and capital gains on your purchase follow standard Indian income tax rules for NRIs.
Q5) How Liquid Is the Resale Market for GIFT City Office Property?
Improving, but still thinner than an established commercial address like BKC. A leased unit with a quality tenant is considerably easier to exit than a vacant one. NRIs planning a short holding period should weight this constraint carefully before committing.
References & Sources
GIFT City official portal — master plan, zone data, and entity statistics
https://giftgujarat.in
IFSCA — GIFT IFSC Key Highlights (1,147+ registrations/authorisations; USD 111bn+ banking assets, as on March 2026)
https://www.ifsca.gov.in
IFSCA — First Foreign Family Investment Fund registration, April 2026
https://www.ifsca.gov.in
Reserve Bank of India — Master Circular on Acquisition and Transfer of Immovable Property in India
https://www.rbi.org.in
Gujarat Real Estate Regulatory Authority (RERA) — project registration verification
https://gujrera.gujarat.gov.in
Income Tax Department — Forms 145 and 146, remittance reporting requirements
https://www.incometax.gov.in
Source note: Regulatory, tax, and pricing figures referenced in this article can change. Readers should confirm current details with official sources and a qualified CA, FEMA specialist, or property lawyer before transacting.