GIFT City Tax Benefits Are Not One Blanket Exemption
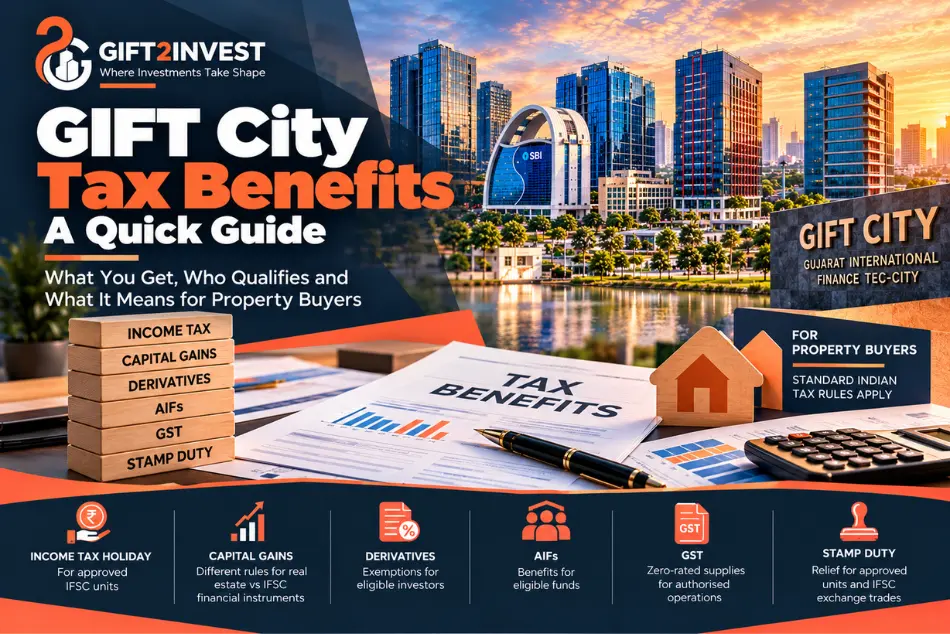
GIFT City tax benefits are real, and for FY 2026-27 they are bigger than they were a year ago. But they don’t work like a blanket exemption over the whole city. What you get depends on the vehicle you use.
Union Budget 2026 stretched the IFSC tax holiday to 20 consecutive years out of 25. That relief belongs to approved IFSC units: banks, fund managers, leasing entities and similar businesses. It doesn’t belong to someone who buys a flat or an office.
This guide covers FY 2026-27. The Income-tax Act, 2025 calls it tax year 2026-27, which older readers will know as assessment year 2027-28. We’ll go through capital gains, derivatives, MAT, NRI withholding and what a property buyer can actually claim.
It’s educational, not tax or legal advice. Confirm your own position with a chartered accountant before committing capital.
GIFT City Tax Benefits at a Glance
Property buyers should read the last column first.
| Benefit | Who It Applies to | Practical Effect | Condition | Real Estate Relevance |
|---|---|---|---|---|
| Income Tax Holiday | Approved IFSC units | No tax on eligible business income for 20 consecutive years out of 25; 15% after | LOA, IFSCA registration, eligible activity | Indirect. More units means more tenants |
| MAT / AMT | IFSC units | 9% on book profit, against 14% general MAT | Operating unit | None for an owner |
| Listed Securities | Non-resident investors | No capital gains on specified securities traded on an IFSC exchange | Foreign-currency settlement | None |
| Derivatives | Non-residents, specified funds | Exempt income on IFSC exchange derivatives and certain OTC contracts | Instrument and counterparty tests | None |
| Category III AIFs | Eligible IFSC funds | Exemption on specified fund income | Fund conditions, sunset dates | None |
| GST | Units and their suppliers | Supplies to SEZ units for authorised operations are zero-rated | Letter of undertaking, authorised use | Only if you lease to an SEZ unit |
| Stamp Duty Relief | Approved units | Relief on specified unit instruments and IFSC exchange trades | Eligibility Certificate | Not for individual home buyers |
| Property Sale and Rent | Individual owners | None. Standard Indian rules apply | Not applicable | This is your position |
Do Not Confuse: Buying an apartment or office in GIFT City doesn’t make you an IFSC unit. It doesn’t unlock the tax holiday, the 9% MAT or any unit-level exemption. Those attach to approved businesses, not property owners.
Who Actually Gets These Tax Benefits?
The label “GIFT City” covers very different tax positions. Check which one is yours.
- Resident individual. A flat or office means standard Indian tax on rent and capital gains.
- NRI or OCI property buyer. The same property tax rules, plus non-resident withholding and FEMA repatriation rules.
- IFSC exchange investor. Non-residents trading specified securities and derivatives in foreign currency can fall under capital gains exemptions.
- AIF or fund participant. Treatment turns on the fund category, its IFSC status and your residency.
- Operating IFSC unit. The holiday, the 9% MAT rate and GST relief sit here.
Same city, same postcode, very different tax bill.
Capital Gains Tax Benefits in GIFT City
Two asset families sit under one name, and they are taxed differently.
Real estate gets no special rate. There is no zero or reduced capital gains rate for flats or offices inside GIFT City. Property held more than 24 months is long term and taxed at 12.5% without indexation, plus surcharge (capped at 15% on long-term gains) and 4% cess. Shorter holds are taxed at your slab rate. Some resident sellers who bought before 23 July 2024 can still choose the older 20% with indexation route. Ask your CA whether you qualify.
IFSC financial instruments are different. When a non-resident transfers specified securities on an IFSC exchange and the statutory conditions, including foreign-currency consideration, are met, the transfer may qualify for the applicable exemption. The exemption applies only to securities covered by the relevant provisions and notifications.
“Concessional” here means no tax in India on that gain. It doesn’t mean no tax anywhere. Your home country may still tax it.
A listed-instrument example. A non-resident buys a USD bond listed on an IFSC exchange for $100,000 and sells it for $112,000. If the bond qualifies as a specified security and the statutory conditions are met, India may not tax the $12,000 gain under this exemption. Your country of residence might, so the after-tax result depends on where you live.
What a property sale looks like after tax. Assume you bought for ₹1.20 crore and sold for ₹1.80 crore. We ignore brokerage and surcharge to keep it clean.
| Step | Sold After 18 Months | Sold After 4 Years |
|---|---|---|
| Headline Gain | Rs. 60 lakh (50%) | Rs. 60 lakh (50%) |
| Tax Rate | Slab rate, say 30% | 12.5% long term |
| Tax Before CESS | Rs. 18 lakh | Rs. 7.5 lakh |
| Add 4% CESS | Rs. 18.72 lakh total | Rs. 7.80 lakh total |
| Gain After Tax | Rs. 41.28 lakh (34.4%) | Rs. 52.20 lakh (43.5%) |
Same headline return, nine points apart after tax. Holding period does the work.
Stamp duty and registration paid at purchase form part of your cost of acquisition and reduce the taxable gain. Keep every receipt.
Derivative Tax Exemptions in GIFT IFSC
Exchange-traded derivatives are standardised contracts, such as GIFT Nifty futures, traded on a recognised exchange. Global funds use them to hedge India exposure without touching the domestic market.
A non-resident’s derivative income on an IFSC exchange, with consideration paid in foreign currency, isn’t taxed as a transfer in India. Those trades also carry no STT or CTT.
For managers, this isn’t a footnote. A fund hedging a dollar book through GIFT Nifty doesn’t lose a slice to transaction taxes on every roll. Over a year of rolling hedges, those savings add up.
Over-the-counter contracts are narrower. Certain OTC and offshore derivative income of a non-resident is exempt where the counterparty is an IFSC banking unit or a qualifying foreign portfolio investor. Contracts outside those conditions follow standard law.
Eligibility Checklist:
- Investor status: non-resident or a specified fund.
- Instrument: a specified derivative or security, not any contract.
- Platform: a recognised IFSC exchange, or an eligible IFSC counterparty for OTC.
- Currency: settlement in foreign currency.
- Time window: several benefits require operations to start by 31 March 2030.
The exemption covers Indian income tax only.
MAT / AMT Benefits and Why They Matter
Minimum Alternate Tax is a floor. If a company’s normal tax falls very low, MAT charges a percentage of its book profit instead. AMT is the same idea for non-company entities such as LLPs.
Budget 2026 cut the general MAT rate from 15% to 14% and made it a final tax. IFSC units stay at 9%. That matters because a unit using the holiday would otherwise pay MAT at the higher rate.
Only approved IFSC units benefit. A buyer of an individual apartment doesn’t file under MAT at all.
Investors don’t pay MAT themselves, but it still matters. An entity’s cost base shapes what a vehicle can charge and what it keeps, so read the structure before you commit.
Illustration: An IFSC fund-management company reports Rs. 10 crore of book profit. At 9% MAT it pays Rs. 90 lakh. At 14% it would pay Rs. 1.4 crore. The Rs. 50 lakh difference stays inside the entity, which can help keep fund costs lower. Whether investors see that in net returns depends on the fund.
NRI and OCI Tax Benefits: TDS and Withholding
TDS isn’t your final tax. It’s tax collected in advance, and your actual liability is settled when you file your Indian return.
Financial vehicles. Interest on deposits with IFSC banking units is exempt for non-residents. Gains on specified listed securities and some fund income also have exemptions. Each depends on how the income is classified, so don’t assume a whole product is TDS-free.
Real estate. Rent paid to an NRI is subject to TDS at the applicable rate under the Income-tax Act, 2025; the effective rate depends on the payment’s classification and applicable provisions. On a sale, long-term gains on property are generally taxed at 12.5% without indexation, while short-term gains are generally taxed at the applicable rates. Buyers may need to deduct tax on the full sale consideration unless the seller obtains a lower- or nil-deduction certificate. Under the new Act, non-resident withholding is covered by section 393(2), which replaces the relevant provisions previously found in section 195 of the Income-tax Act, 1961.
Double Taxation Avoidance Agreements can give credit in your country of residence. They rarely remove Indian tax on property.
Where applicable, surcharge and cess can affect the effective tax or withholding amount. Have a CA compute the amount before the deed is signed.
Repatriation depends on your funding route. Repatriation of sale proceeds for up to two residential properties may be permitted under the NRE/FCNR route, subject to FEMA conditions and the original funding route. Amounts credited to NRO accounts are generally subject to the applicable USD 1 million per financial year remittance limit, documentation and tax-compliance requirements.
Eight-Point NRI Checklist:
- Confirm residential status by days of stay, not by passport or OCI card.
- Align your PAN across the sale deed, bank accounts and tenancy.
- Fix the funding route (NRE, NRO or FCNR) before paying.
- Classify the asset: residential, commercial or financial instrument.
- Plan for sale TDS and apply for a lower deduction certificate if needed.
- Make sure tenants deduct rent TDS correctly and issue certificates.
- Prepare the required repatriation paperwork and confirm whether Forms 145 and 146 are relevant to your transaction. These forms concern information for payments to non-residents and an accountant’s certificate; they are not general-purpose property-repatriation forms.
- File your Indian return and check DTAA credit at home.
Does Buying GIFT City Real Estate Give You These Tax Benefits?
No. Buying an apartment doesn’t make you an IFSC unit. The question is whether GIFT City tax benefits reach a property owner, and the answer depends on the asset.
- Residential units. Standard rules on rent and capital gains.
- DTA commercial. Standard rules. Taxable commercial rent may attract 18% GST, depending on the supply and the applicable registration and exemption rules.
- SEZ office leased to an approved unit. Renting to an SEZ unit for authorised operations can be zero-rated, subject to a letter of undertaking and other conditions.
Rental income is taxed under normal income-tax rules. Yield, entry price, holding period and transaction costs decide your return, not corporate incentives.
Do not treat a single gross-yield range as a verified market-wide figure. Calculate yield from the specific property’s current achievable rent and total acquisition cost; account separately for maintenance, vacancy, taxes and transaction costs. That net figure is what you compare against a fixed deposit, not the brochure yield.
Where the state-level savings actually sit. Certain eligible units may qualify for stamp duty and registration relief under applicable Gujarat SEZ/IFSC provisions. Confirm the specific instrument, unit eligibility and certificate requirements with the relevant authority before relying on the relief. An individual flat buyer generally pays the applicable Gujarat stamp duty and registration charges, calculated under the current rules. Confirm current rates on the state portal.
If you’re buying space for your own IFSC entity, this is where the numbers get interesting: unit-level stamp duty relief, zero-rated GST on rent and the 20-year holiday. Our SEZ and DTA listings state the zone upfront, so you can check eligibility before you shortlist.
Tax Benefits for Funds, Family Offices and Investment Vehicles
Large families and funds set up inside the IFSC because it gives them a regulated, onshore wrapper. IFSCA now has 1,147 registrations and authorisations, with banking assets above USD 111 billion as of March 2026.
Two tax layers matter. The first is the entity or fund layer, where holiday, MAT and exemption rules apply. The second is what reaches the investor, which depends on residency and distribution type.
Placement matters. A fund inside the IFSC can access holiday and exemption rules a mainland fund can’t. A Family Investment Fund is not automatically a property-holding vehicle, so confirm what the specific fund, its investment strategy and its approval terms may legally hold.
Family Investment Funds must have and maintain a minimum investment of USD 10 million within three years of registration; this is a minimum-investment requirement, not a USD 10 million net-worth threshold. IFSCA approved its first Foreign Family Investment Fund in April 2026. A good structure can facilitate cross-border investment, but each family’s tax outcome is its own.
How GIFT City Tax Benefits Can Affect Investment Returns
Work in this order: gross capital, headline yield, tax, holding costs, net yield. A low tax rate only helps if entry price and exit liquidity also line up.
Here’s a seven-year comparison on Rs. 1.5 crore. The property case assumes Rs. 4.5 lakh a year of net rent after tax and costs, 5.9% stamp duty and registration at purchase, and 1% selling cost. The financial case assumes a USD-denominated IFSC-listed instrument, with no home-country tax and no currency move.
| Scenario | Value at Exit | India Tax Paid | Total Gain After Tax |
|---|---|---|---|
| Property, 8% yearly price growth | Rs. 2.57 crore | Rs. 12.4 lakh | Rs. 1.15 crore (72%) |
| Property, 4% yearly price growth | Rs. 1.97 crore | Rs. 4.8 lakh | Rs. 63 lakh (40%) |
| IFSC-listed instrument, 7% yearly | Rs. 2.41 crore | Nil | Rs. 91 lakh (61%) |
The tax-free asset didn’t win automatically. Property beat it when growth was strong and lost when growth was slow. Return assumptions, currency and home-country tax drive the answer. These are illustrations, not forecasts.
Common Misconceptions About the Tax Benefits
- Every property owner gets a tax holiday. The holiday belongs to approved IFSC units. A property owner pays standard tax on rent and gains.
- Property exits carry zero capital gains tax. Property sales follow mainland rules, at 12.5% for long-term gains. Exemptions apply only to specified IFSC securities.
- NRI transactions are automatically TDS-free. Rent attracts 30% TDS and sale proceeds attract withholding. Only certain IFSC income streams are exempt.
- Every derivative is untaxed. The exemption covers specified derivatives on IFSC exchanges and certain OTC contracts. Everything else follows standard law.
- Individual buyers inherit MAT reductions. The 9% MAT applies to IFSC units. It has no effect on a personal property purchase.
Tax Due-Diligence Checklist Before Investing
- Confirm your status: resident or NRI/OCI.
- Classify the asset: residential, commercial, SEZ office or financial instrument.
- Verify the zone, IFSC/SEZ or DTA, from the allotment documents.
- Match the rules to FY 2026-27 and check sunset dates.
- Confirm RERA registration on the Gujarat RERA portal.
- Model the post-tax outcome, including stamp duty and holding costs.
Then sit down with a local chartered accountant before any money moves.
Rules move. A step that was correct last year may have changed, so re-check each one on the day you transact.
Look at the After-Tax Return, Not Just the Tax Benefit
The zone’s advantages are structural, but they vary by vehicle. Several exemptions carry a 31 March 2030 sunset for new operations, and the 20-year holiday window starts now for new units. That’s a real reason to act on structuring early, not a reason to rush a purchase.
Keep property and fund decisions separate. A flat is a real estate play. A fund or unit is a tax-structured one.
The investors who do well treat tax as one input, not the thesis. Entry price, yield and exit liquidity still decide the outcome.
GIFT City tax benefits are worth understanding before you buy, not after. Browse zone-verified residential and commercial listings on Gift2Invest.com, then take your numbers to a local chartered accountant.
FAQs
What Are the Main Tax Benefits of GIFT City?
For IFSC units: a 20-year holiday out of 25, 9% MAT and GST relief. For non-resident investors: exemptions on specified IFSC securities and derivatives. For property buyers: none beyond standard rules.
Does GIFT City Have Zero Capital Gains Tax?
Only on specified IFSC-listed instruments for eligible non-residents. Real estate is taxed at standard rates.
Are Derivatives Tax-Free in GIFT City?
Specified derivatives on IFSC exchanges, and certain OTC contracts with IFSC banking units or qualifying FPIs, are exempt for non-residents. Other contracts aren’t.
Do NRIs Get TDS Exemption in GIFT City?
Not across the board. Some IFSC income is exempt, but property rent and sale proceeds attract TDS.
Does Buying an Apartment in GIFT City Give Tax Benefits?
No. You pay standard stamp duty, tax on rent and capital gains tax.
Is Rental Income From GIFT City Property Tax-Free?
No. It’s taxable under normal income-tax rules.
Sources and References
Checked October 2026. Tax rates, section numbers and sunset dates change. Verify the current position before you rely on any figure here.
GIFT City and IFSC: Official Information
GIFT City Official Portal
https://giftgujarat.in
GIFT City, Doing Business in GIFT City (GST, stamp duty and IFSC incentives overview)
https://api.giftgujarat.in/public/tool-guiedes-for-setting/DoingBusinessInGIFTCity.pdf
IFSCA official website and GIFT IFSC key highlights (March 2026)
https://www.ifsca.gov.in
Tax Benefits, Incentives and Union Budget Updates
IFSCA and EY, GIFT IFSC Tax Benefits (sunset dates extended to 31 March 2030)
https://ifsca.gov.in/Document/10_EY-GIFT_tax_benefits_050225.pdf
PwC Worldwide Tax Summaries, India Corporate: Significant Developments (Finance Act 2026)
https://taxsummaries.pwc.com/india/corporate/significant-developments
PwC Worldwide Tax Summaries, India Corporate: Tax Credits and Incentives
https://taxsummaries.pwc.com/india/corporate/tax-credits-and-incentives
EY Tax News, India Releases Union Budget 2026 (IFSC tax holiday, MAT at 14% and IFSC MAT unchanged at 9%)
https://taxnews.ey.com/news/2026-0351-india-releases-union-budget-2026
PRS Legislative Research, Union Budget 2026–27 Analysis
https://prsindia.org/budgets/parliament/union-budget-2026-27-analysis
KPMG India, Budget 2026: A Clearer, Friendlier and Investment-Ready Income Tax Regime (Income-tax Act, 2025 effective 1 April 2026)
https://kpmg.com/in/en/blogs/2026/02/budget-2026-a-clearer-friendlier-and-investment-ready-income-tax-regime.html
Income Tax Department, Tax-Free Incomes
https://www.incometaxindia.gov.in/w/tax-free-incomes
NRI Taxation, Capital Gains and Tax Deducted at Source (TDS)
Income Tax Department, Non-Resident Benefits Allowable
https://www.incometaxindia.gov.in/w/non-resident-benefits-allowable
Business Standard, Property Sales by NRIs: Tax Rules and Life Without Indexation
https://www.business-standard.com/finance/personal-finance/property-sales-by-nris-experts-explain-tax-rules-life-without-indexation-125072100424_1.html
NRI Information, Selling Property in India as an NRI (TDS, capital gains and repatriation)
https://nriinformation.com/property/selling-property-nri
Income Tax Department, Income-tax Act, 2025, Section 393 (TDS, including payments to non-residents)
https://www.incometaxindia.gov.in/w/section-393-6
Income Tax Department, Capital Gains Guidance (holding periods and tax rates)
https://www.incometaxindia.gov.in/w/capital-gain
Income Tax Department, Income Tax Forms Downloads (Forms 145 and 146)
https://www.incometax.gov.in/iec/foportal/downloads/income-tax-forms?field_income_tax_act_forms_target_id=2
Stamp Duty, Registration and Property Compliance
Dhaval Vussonji & Associates, via Mondaq, Stamp Duty in Modi’s GIFT City (Gujarat SEZ Act, 2004, Section 21)
https://www.mondaq.com/india/sales-taxes-vat-gst/1472944/stamp-duty-in-modis-gift-city
Gujarat e-Stamping Portal (GARVI), for current stamp duty and registration rates
https://garvi.gujarat.gov.in
Gujarat Real Estate Regulatory Authority (GujRERA)
https://gujrera.gujarat.gov.in
GST, IGST and Zero-Rated Supplies to SEZ Units
Central Board of Indirect Taxes and Customs (CBIC), Integrated Goods and Services Tax Act, Section 16 (zero-rated supplies)
https://cbic-gst.gov.in/hindi/IGST-bill-e.html
ITAT Online, GIFT City Hits and Misses: Direct and Indirect Taxation Aspects (including discussion of IGST Act, 2017, Section 16)
https://itatonline.org/digest/articles/gift-city-hits-and-misses-direct-and-indirect-taxation-aspects
Family Investment Funds and International Investment Structures
IFSCA, Current Family Investment Fund Eligibility Regulation
https://www.ifsca.gov.in/LegalDatabase/VersionDetailView?CatEncryptedId=mizvnmwVAgs%3D&EncryptedId=-ubwPcis0NY%3D&Index1Id=6&Index2Id=884&LegalDetaileId=47&SubEncryptedId=KMZ5djvTZ4U%3D&VersionNumber=V1
IFSCA, First Foreign Family Investment Fund Registration (20 April 2026)
https://www.ifsca.gov.in/CommonDirect/ViewFile?fileName=Press_Release_FIF_1_20260420_0105.pdf&id=d575554ec59b09e7fde503d3a8d33f60
Source Note: This article is general information, not legal, tax or investment advice. Confirm your position with a qualified chartered accountant or FEMA specialist before transacting.