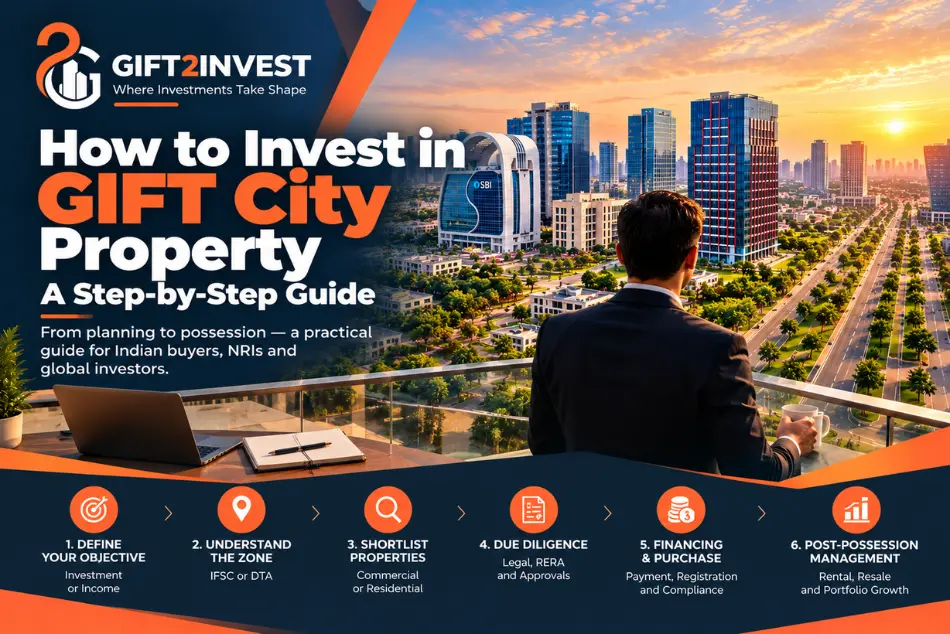
How to Invest in GIFT City Property: Start With the Right Thesis
Most people arrive at the question of how to invest in GIFT City property with a rough idea that it is a good opportunity. That part is widely understood at this point. What is less clear — and where most first-time buyers lose time or money — is the process. What do you actually do, in what order, and what is specific to GIFT City that does not apply anywhere else in India?
This is a practical guide through that process. It covers every stage, from defining what you want to achieve to managing the asset after possession. The steps are specific to GIFT City because the market is specific. A standard property buying checklist will leave gaps here that can be expensive.
Step 1: Define What You Are Actually Buying
Before looking at a single listing, the most important question to answer is what role this investment plays in your portfolio. The answer changes everything about what you should buy.
GIFT City has two fundamentally different investment products under one city umbrella.
The first is commercial IFSC space. This is an income asset. A leased office unit with an established institutional tenant gives you predictable cash flow, backed by a long lease. It behaves more like a bond with capital upside. If you need yield visibility from near day one, this is the right product.
The second is residential. This is a capital appreciation play. Rental yields are real but not the point. The thesis is the gap between what you pay today and what the city’s property values will be when it reaches operational maturity. This requires a genuine 7 to 10-year horizon. If you do not have that horizon, residential in GIFT City becomes a carry problem, not a wealth-building strategy.
Neither is automatically right. They serve different financial objectives. Confusing the two — buying residential expecting it to yield like commercial, or buying commercial expecting appreciation like residential — is the single most common mistake buyers make here.
Write down your objective before you search for property. It will eliminate most listings immediately and save months of confusion.
Step 2: Understand the Zone — The Filter That Changes Everything
GIFT City has two main commercial zones, and which one a property sits in determines your tenant universe, your pricing power, and your risk profile. This is not a detail — it is the most important variable on any listing.
The IFSC, or International Financial Services Centre, is where regulated financial entities operate. Banks, fund managers, insurance firms, aircraft leasing SPVs, bullion exchange participants — these tenants must maintain a physical presence within the IFSC boundary to hold their IFSCA licenses. The address is a regulatory requirement, not a preference. That creates a structural demand floor with no equivalent anywhere else in India.
The Domestic Tariff Area, or DTA, is the non-IFSC part of GIFT City. Infrastructure is the same — same district cooling, same utility systems, same security. But demand here responds to general economic conditions rather than IFSCA policy expansion. It is effectively a well-run IT and business park, not a mandated-occupancy financial zone.
For residential buyers, the distinction is about proximity. The professionals most likely to rent in GIFT City — compliance officers, fund managers, fintech executives — want to be close to the IFSC towers where they work. Residential projects near the IFSC core have faster rental uptake than those on the periphery.
Zone classification should be confirmed from the GIFT City Development Corporation allotment document. Not the developer brochure. If a sales team cannot produce that document on request, that is a flag worth noting before you go further.
Step 3: Shortlist Properties Using GIFT City-Specific Criteria
The criteria that matter for shortlisting in GIFT City are different from those in a standard property search.
For commercial IFSC space, floor specification is the first filter. IFSC-registered financial entities have baseline requirements — power redundancy at minimum N+1, raised flooring, financial-grade broadband, dedicated cooling, and physical access control. Not every building in GIFT City delivers all of these. A commercial unit without the right infrastructure will not attract institutional tenants regardless of its zone classification. Ask for the building’s mechanical and electrical specifications upfront.
For residential, the key variable is distance from the IFSC core. Projects closest to the operational tower cluster — the concentrated financial district you see in every photograph of GIFT City — have the strongest rental demand and the clearest resale case. Projects further out are cheaper but require a longer wait for the surrounding city to fill in. That is not inherently wrong, but it demands a 10-year horizon, not a 7-year one.
For both commercial and residential: check whether the property is in an operational building or under construction, and who the developer is. These two factors carry more weight in GIFT City than in most Indian markets, for reasons explained in Step 5 below.
Step 4: Run Due Diligence That Is Specific to This Market
Standard property due diligence — title search, RERA check, builder track record — all still applies. GIFT City adds additional layers that most buyers skip because they do not know to look for them.
Verify the RERA Registration
All GIFT City residential and commercial projects fall under Gujarat RERA. Pull the RERA registration document and check the stated possession date. Then check the same developer’s previous GIFT City projects — were they delivered on or near schedule? A developer with a clean record elsewhere in Gujarat is not automatically reliable inside a Special Investment Region. The complexity of building within GIFT City’s SEZ environment is genuinely different.
Check the Allotment Documentation
The GIFT City Development Corporation issues allotment letters to developers for each project. This document confirms zone classification, permitted use, and land parcel details. It is the primary source of truth for what the property actually is.
For Commercial: Confirm Existing Tenancy or LOI
A vacant commercial unit and a leased commercial unit are completely different investments. A unit with a signed lease from an IFSC-registered entity gives you income from possession day. A vacant unit means you are underwriting the leasing yourself — which requires time, negotiation, and some familiarity with what IFSC tenants need. If yield visibility matters to you, only buy with a tenant or a credible letter of intent in place.
Calculate Maintenance Charges Into Your Yield
GIFT City’s premium infrastructure has a cost. Maintenance charges here are higher than most residential societies in Ahmedabad or Gandhinagar. This is often underestimated in yield calculations. Get the exact maintenance charge per square foot from the developer, then run your net yield number, not just the gross.
Step 5: Evaluate the Developer — Specifically for GIFT City
Developer credibility matters everywhere. In GIFT City it matters more, because delivering inside a Special Investment Region requires navigation of GIFT City Development Corporation approvals, SEZ-specific construction protocols, and utility connection processes that do not exist in a standard development.
Developers with a proven record inside GIFT City specifically — completed buildings, on-schedule possession, no post-handover disputes — are in a different risk category from those doing their first project here. Hiranandani, Sobha, Brigade, and Savvy are among those with established presence and delivery history inside the city.
For newer developers building in GIFT City for the first time, their Gujarat track record is the next best indicator. Clean delivery, no significant RERA complaints, a funded project with a credible construction schedule. The absence of any of these is worth pausing on.
Ask specifically about construction stage funding. Under-construction projects in GIFT City should have their construction funded by project revenue plus developer equity — not entirely dependent on future buyer instalments. A project that needs each new booking to fund the next slab is a financing risk, not just an execution risk.
Step 6: Structure Your Financing Correctly
Most GIFT City property purchases are financed through a combination of equity and home loan. Getting the ratio right is more important here than in most markets because of the carry cost dynamic.
GIFT City residential yields 3 to 4 percent gross. If you borrow at 9 percent, your net carry cost — the difference between what your loan costs and what the property earns — is approximately 5 to 6 percent of the asset value per year. On a 1 crore property, that is Rs. 50,000 to 60,000 coming out of your pocket each month, net of rent.
Over a 7-year hold, cumulative carry runs to a significant number. The appreciation needs to meaningfully exceed that figure to make the investment work. At 50 to 60 percent appreciation over 7 years — which is the reasonable case given the infrastructure catalysts in the pipeline — the maths is sound. At 20 percent, it is tight. Model both scenarios before committing.
A higher equity contribution reduces carry and makes the hold more comfortable. Buyers with 50 to 60 percent equity have much more flexibility than those who have borrowed 80 percent of the purchase price. If your loan-to-value is high, make sure your hold horizon is long enough to absorb the carry.
Standard home loans from Indian banks apply to GIFT City residential purchases. Some lenders have more experience with GIFT City projects than others — it is worth asking specifically. NRI buyers can access home loans through NRI lending products, but the documentation process benefits from using a banker who has done GIFT City transactions before.
Step 7: The Booking and Transaction Process
The booking process in GIFT City follows standard Indian real estate practice at the legal level — a booking amount, an allotment letter from the developer, and subsequently a registered Agreement for Sale or Leave and License. For commercial properties, a Leave and License agreement is the standard leasing instrument.
A few things to confirm before signing any booking agreement:
- The project’s RERA registration certificate
- The GIFT City Development Corporation allotment letter confirming zone classification and permitted use
- Title documentation for the land parcel
- Approved building plan and occupancy timeline
- For commercial: floor specification sheet covering power, cooling, and data infrastructure
For properties within the IFSC zone, commercial lease agreements sometimes include rent denominated in USD or escalation benchmarked to USD rates, particularly with foreign bank branches or international fund managers as tenants. If the lease is already in place, review these terms carefully before the acquisition. Currency exposure for the landlord is real.
Engage a property lawyer with specific experience in Gujarat RERA and SEZ projects. General real estate lawyers unfamiliar with SEZ documentation can miss gaps that are expensive later. The additional cost of a specialist is minor relative to the transaction size.
Step 8: Managing Your GIFT City Asset After Possession
Buying the property is the beginning, not the end. How you manage it post-possession determines whether the investment thesis actually delivers.
For Residential
Furnishing is not optional for the IFSC professional and expat tenant segment. Furnished or semi-furnished units lease faster and at higher rents. An unfurnished flat in GIFT City can sit vacant for months while a comparable furnished unit fills in weeks. Budget furnishing costs into your total investment figure upfront.
If you are an NRI or out-of-city investor, professional property management is worth the cost. GIFT City’s tenant segment — senior banking professionals, returning NRIs, expat executives — expects responsive management. Managing from a distance without a local property manager creates tenant experience problems that lead to early exits and re-leasing costs.
For Commercial
Once leased, a GIFT City IFSC commercial unit with an institutional tenant largely manages itself. The lease structure does the work. The critical ongoing task is monitoring IFSCA’s regulatory announcements — new permitted activities, new entity registrations, updated frameworks — because these directly affect demand for your space when the current lease comes up for renewal.
Fit-out periods between tenants can be long. An IFSC bank branch or fund management office may need 6 to 9 months to customise a floor to their requirements. Budget for vacancy between tenancies when modelling net yield over the full holding period.
Tracking the Investment Over Time
For GIFT City specifically, the leading indicators to watch are: IFSCA entity registration count, active banking asset size (currently over USD 100 billion as per giftgujarat.in), progress on metro connectivity, university campus scale-up, and retail/hospitality occupancy. These are the variables that actually move residential and commercial values here. General Ahmedabad property market trends are largely irrelevant to GIFT City’s trajectory.
Wrapping Up: How to Invest in GIFT City Property
Knowing how to invest in GIFT City property is not complicated, but it is specific. The steps that matter here are different from anywhere else in India — the zone check, the allotment documentation, the floor specification for commercial, the carry cost modelling for residential, the developer track record within the SEZ. Missing any of these is where most investors run into problems.
The fundamentals remain strong. GIFT City crossed 1,000 operational entities and over USD 100 billion in banking assets. Two universities are now active on campus. The IFSC entity base keeps growing with each new IFSCA regulatory expansion. The infrastructure — India’s first district cooling system, automated waste management, utility tunnels, C4 control centre — works as designed.
Knowing how to invest in GIFT City property means matching the right product to your actual objective, verifying what you are buying against official documentation rather than brochures, and structuring your hold correctly for what this market delivers — not what you hope it delivers.
The investors who have done well here did not get lucky. They understood the process before they committed capital, and they gave the investment the time it needed to work.
FAQs: How to Invest in GIFT City Property
Q1) Can I Buy GIFT City Property as an NRI Without a PAN Card?
NRIs can purchase property in GIFT City under standard RBI guidelines for immovable property in India. A PAN card is typically required for property registration. Confirm the specific documentation requirements with a qualified legal advisor, as the structure can vary depending on whether you are buying as an individual or through an entity.
Q2) What Is the Minimum Ticket Size for GIFT City Residential?
Residential units typically start from around Rs. 1 crore for smaller configurations in mid-range projects within or adjacent to the GIFT City zone. Premium IFSC-zone projects run significantly higher. Commercial units vary widely — from standalone offices of a few hundred square feet to full floors.
Q3) Is GIFT City Covered Under Gujarat RERA?
Yes. All GIFT City residential and commercial projects fall under Gujarat RERA. Checking RERA registration status before signing any booking or allotment agreement is standard hygiene. The RERA document will also show the builder’s stated possession date, which you can cross-reference against their delivery history.
Q4) How Long Does the Purchase Process Take From Booking to Possession?
For ready-to-move properties, legal registration typically takes 4 to 8 weeks after payment. For under-construction properties, the possession timeline depends on construction stage and ranges from 1 to 4 years. Get the RERA-stated possession date and check it against the developer’s on-ground progress before committing to an under-construction project.
Q5) Is GIFT City Commercial Property a Better First Investment Than Residential?
For investors who need income visibility from near possession, commercial with an existing IFSC tenant in place is the cleaner entry point. Gross yields of 6 to 8 percent on quality IFSC commercial are meaningfully higher than residential yields. For investors playing a 7 to 10-year capital appreciation thesis and comfortable with lower near-term yield, residential near the IFSC core has a stronger upside case. The right answer depends on what you need from the investment, not what sounds better.